Government probes whether Poundland's US owners are pushing the chain towards collapse as 12,000 jobs hang in the balance
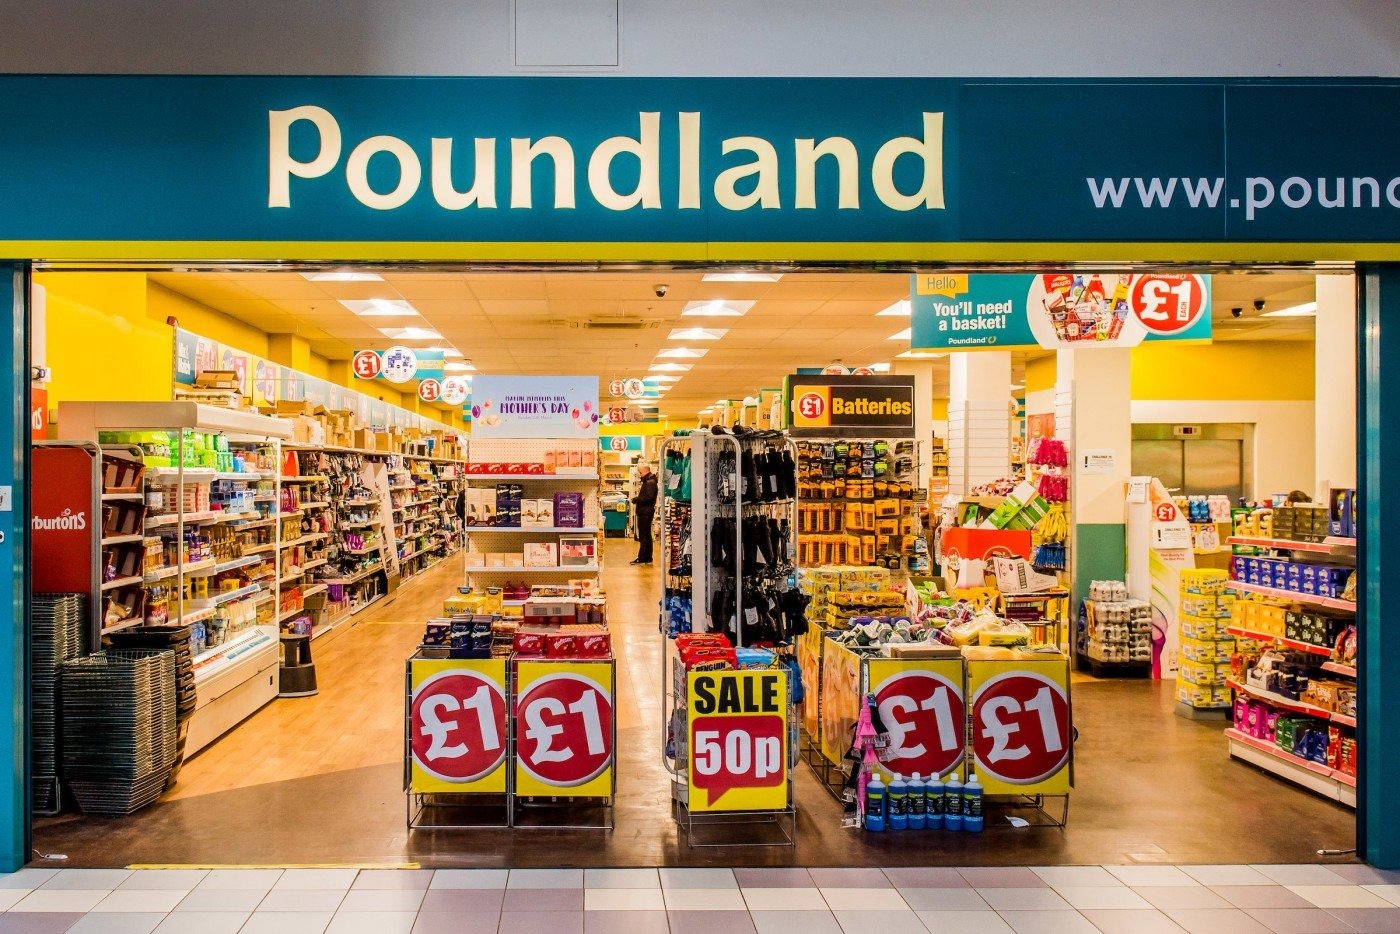
Gordon Brothers, the US investment firm that bought Poundland for £1 last year, is standing in the way of a takeover and is thought to prefer a break-up of the chain as the surest route to recovering a £30m shareholder loan. The government has launched an investigation into whether the owner is intentionally driving the retailer toward insolvency. If administration begins, more than 12,000 employees could lose their jobs just weeks before Christmas.
Three board members appointed to oversee the sale — Andrew Kirkpatrick, Stephen Welch and Dominic Young — are close to quitting in frustration.
Irish firm Martin Property Group, the leading bidder, offered full repayment of the £30m loan, but Gordon Brothers turned down the proposal over concerns about the timing.
With around 600 UK stores, Poundland would represent one of the largest high street failures in years if it tips into insolvency.